

Tax Planning for School Bus Contractors: 2008 and Beyond
School bus contractors are facing higher fuel costs, increasing vehicle prices coupled with forthcoming higher emission control standards, and sho...
School bus contractors are facing higher fuel costs, increasing vehicle prices coupled with forthcoming higher emission control standards, and shortages of qualified drivers among many concerns. At the same time, overall school budgets are being pinched by reduced revenues from our challenged economy.
As daunting as these factors appear, proper tax planning can mitigate some of these higher operating costs.
With the advent of a recession and the general decline in business activity, Congress has passed three pieces of tax legislation over the past year that provide, among other things, incentives for businesses. In many instances, these legislative changes to the Internal Revenue Code impact tax year 2008 and beyond.
The three tax acts enacted are:
Small Business and Work Opportunity Tax Act of 2007 (SBWOTA) P.L. 110-28
Economic Stimulus Act of 2008 (ESA) P.L. 100-185
Emergency Economic Stabilization Act of 2008 (EESA) P.L. 110-343 The following is a summary of the major provisions impacting tax year 2008 as related to school bus contractors, along with specific tax-planning ideas.
Section 179 expense deduction
The election for taxpayers to expense the cost of certain fixed assets has always been well received, and provisions already in place under I.R.C. §179 (Sec. 179) allowed taxpayers to do so.SBWOTA increased the maximum amounts starting with tax year 2007 and indexed these deductions for inflation so they would continue to increase. Also, the phase-out threshold for this deduction was increased.
Under ESA, the amounts were superseded for 2008 only, by raising the limit of the I.R.C. §179 to $250,000 with a phase-out threshold for Sec. 179 property placed in service to $800,000 (this increased from $128,000 and a threshold of $510,000). However, in tax year 2009, it is scheduled to revert back to the SBWOTA indexed limits.
Tax planning: 2008 is a key year to maximize the benefit of immediately writing off assets rather than depreciating them over several years. If you purchased less than $800,000 of qualifying assets (buses, trucks, machinery, office equipment, furniture, computers, and gasoline storage tanks and pumps), you are eligible for a first-year deduction of up to $250,000. (If asset purchases exceed $1,050,000, Sec. 179 write-offs are not allowed.)
If you purchased $250,000 or less of qualifying assets, the entire amount is deductible in 2008. In 2009, the limits revert back to the SBWOTA rules of a maximum credit of $133,000. In 2010, the limits revert back to the pre-2003 levels of $25,000 Sec. 179 expense with a $200,000 threshold.
Since the ESA change is effective for fiscal years ending after June 1, 2008, fiscal year taxpayers get the higher limit of $250,000 until the end of their fiscal year (e.g., contractors on a July to June year get the higher limit on assets in use before July 2009).
Bonus depreciation
ESA amended I.R.C. § 168 to allow taxpayers to take an additional first-year 50-percent bonus depreciation of the adjusted basis of qualifying property acquired in 2008. This involves property with a 20-year life or less and is eligible by definition for the modified accelerated cost recovery system (MACRS). Eligibility is also available to off-the-shelf computers, qualified leasehold improvement property and water utility property.In order to utilize this bonus depreciation, the asset’s original use, acquisition and placement in service must occur during 2008. The taxpayer must reduce the adjusted basis for the bonus depreciation before calculating the normal depreciation on the reduced basis. (There has been discussion of a “Workers, Retirees, and Employer Recovery Act of 2008” extending the Sec. 179 and bonus depreciation rules for 2008 into 2009, but nothing had been passed as of press time.)
Tax planning: If the taxpayer has taken the Sec. 179 deduction and there is a remaining basis on the property, the taxpayer can take bonus depreciation on the remaining basis.
For example, assume the entire $250,000 of qualifying assets is written off (Sec. 179) and one bus remains to be depreciated. The purchased price of the bus is $70,000. A bonus depreciation deduction of $35,000 (50 percent) is allowed along with the normal depreciation on the remaining basis of the bus ($70,000 cost less $35,000 bonus depreciation results in $35,000 remaining basis). Assuming a five-year life using MACRS, another 20 percent of the remaining basis — $7,000 — is taken as additional depreciation. Thus, a $70,000 bus results in $42,000 ($35,000 bonus plus $7,000 regular depreciation) being written off in the first year, making the after-tax cost of the vehicle very attractive.
Another scenario with attractive tax benefits is buying a heavy SUV (over 6,000 pounds) for your business. Using Sec. 179 rules, half of the vehicle can be expensed immediately or $25,000. The remaining basis of $25,000 is subject to the 50-percent bonus depreciation, resulting in another write-off of $12,500. The remaining basis of $12,500 is subject to the MACRS depreciation of 20 percent in the first year, or $2,500. Thus, $40,000 of the vehicle can be expensed in the first year of use.
Passenger automobiles
Taxpayers are limited on the amount of first-year depreciation they can take for a passenger automobile. Under I.R.C. §280F(a)(1)(A)(i), it is limited to $3,060. ESA increases this first-year amount by $8,000 to allow taxpayers to utilize the provisions of bonus depreciation as outlined above (maximum first-year to $11,060; and $11,260 for vans or trucks).Tax planning: This provision assumes the automobile is predominantly used for business. Taxpayers should take advantage of this 2008 tax savings provision along with buyer savings the manufacturers are currently offering.
Energy incentives
Tax credits are available for qualified alternative fuel motor vehicles. Buses can be newly purchased or converted from an existing diesel/ gas unit and retrofitted for use with alternative fuels.The credit depends on the weight of the bus and the incremental allowable cost (the cost of the vehicle over the suggested retail value of a comparable diesel bus). Generally, the credit ranges from 50 to 80 percent and can offer tax credits of almost $10,000 on a newly purchased bus.
The credit is part of the general business credit and may be carried back one year and forward for 20 years (IRS form 3800). The bus must be purchased before Jan. 1, 2011.
Alternative fuels
EESA also extends a number of existing alternative energy tax incentives. Prior law allowed a tax credit for using alternative fuels (credit depends on the type of fuel).Contractors using propane or biodiesel fuel mixtures could receive a 50- cent per gallon credit. EESA increased the biodiesel credit to $1 per gallon to match the same credit for using agribiodiesel.
EESA also extends the alternative fuel tax credit three additional months, to Dec. 31, 2009.
Tax planning: Receiving the credit requires being the alternative fueler with respect to the fuel and registered under §4101. Thus, a contractor must pump the fuel into the tank of their buses. Generally, if you are using alternative fuel and you do not have a refueling station, the credit is provided to the person pumping the fuel. If your transportation arrangement allows for the school district to purchase fuel and you pump from their tanks, the credit goes to the school district.
Before using alternative fuel buses, make certain you can capture these credits by installing an alternative fueling station or having the credits passed to you from the school district.
Alternative refueling station
Installing an alternative refueling station after Dec. 31, 2005, to store and dispense clean-burning fuel into buses provides a 30-percent tax credit up to $30,000. EESA extends the alternative refueling station credit one additional year, to Dec. 31, 2010. The credit is part of the general business credit and may be carried back one year and forward for 20 years.Tax planning: If you are considering using alternative fuels, contact the provider of the fuel to get a dispensing unit installed on your property. This ensures you get the credit for pumping each gallon of alternative fuel as well as the refueling station credit. The refueling station credit does not apply to structural components or a building.
Other tax-saving ideas
Hiring disadvantaged workers: SBWOTA renewed the Work Opportunity Tax Credit (WOTC) through Aug. 31, 2011. Under this program, companies hiring employees in groups facing economic challenges, such as welfare recipients, high-risk youths and veterans, can receive tax credit for a percentage of qualified wages paid to these employees for the first two years of employment.Energy-efficient commercial building deduction: If you own a commercial building and improve the energy efficiency of interior lighting systems; heating, cooling, ventilation, and hot water systems; or the building envelope, an immediate deduction is available rather than depreciating the cost over the useful life of the building. A maximum deduction of $1.80 per square foot is available. EESA has extended this Sec. 179D provision for five additional years to Dec. 31, 2013.
Real estate taxes: If your business is located in a community where real estate prices are declining, consider appealing the real estate assessment on your property to reduce real estate taxes.
Taking action
The current economic climate will motivate businesses to take advantage of the tax incentives provided by Congress in recently enacted legislation. Businesses with purchase equipment needs should evaluate the tax savings and the respective time frame to utilize these benefits. Please consult your tax planning professional for guidance in these areas.Bruce A. Leauby is an associate professor at LaSalle University in Philadelphia. He can be reached atleauby@ lasalle.edu. Jack Zook, an assistant professor at La- Salle University, can be reached atzook@lasalle.edu.
More Management

5 Questions: How CharterUP Brought a Marketplace to Student Transportation
What does it take to bring a transportation marketplace into K-12? Hear firsthand what CharterUP has learned about the unique needs of schools and bus operators.
Read More →
EverDriven Expands TripCentral Transportation Management Platform to All Partner Districts
The platform provides school districts with real-time trip tracking, student transportation scheduling tools, and pickup and drop-off management capabilities.
Read More →
6 School Transportation Trends to Watch: 2026 District Survey Results
School bus buying is up, fuel choices are shifting, and driver shortages persist. This and more in the latest K-12 public school survey, plus the largest fleets in the U.S.
Read More →
The 100 Largest School Bus Fleets in America: 2026 Rankings
Which public K-12 school districts are the largest in the nation in terms of bus fleet size? Here are the new standings of the top 100 district fleets.
Read More →
EverDriven Launches Route Consolidation Calculator to Estimate Diesel Savings
As diesel prices hit record highs, the largest alternative transportation provider says a 10% route consolidation could save a 120-route district more than $78,000 a year in fuel alone.
Read More →
Zum Secures Continued Financing Support for School Bus Expansion
Generate Private Credit has financed approximately $75 million in school bus deployments across three states, supporting more than 500 buses as Zum expands across the county.
Read More →
Beyond Discipline: A Different Approach to Student Behavior on the Bus
After implementing a dean of students program in Oregon, North Clackamas is seeing positive improvements. Here’s how it worked. The Route is brought to you by IC Bus.
Read More →
A Dean of Transportation's Different Approach to Student Behavior on the School Bus
After implementing a dean of students program in Oregon, North Clackamas is seeing positive improvements on the bus. Here’s how it worked.
Read More →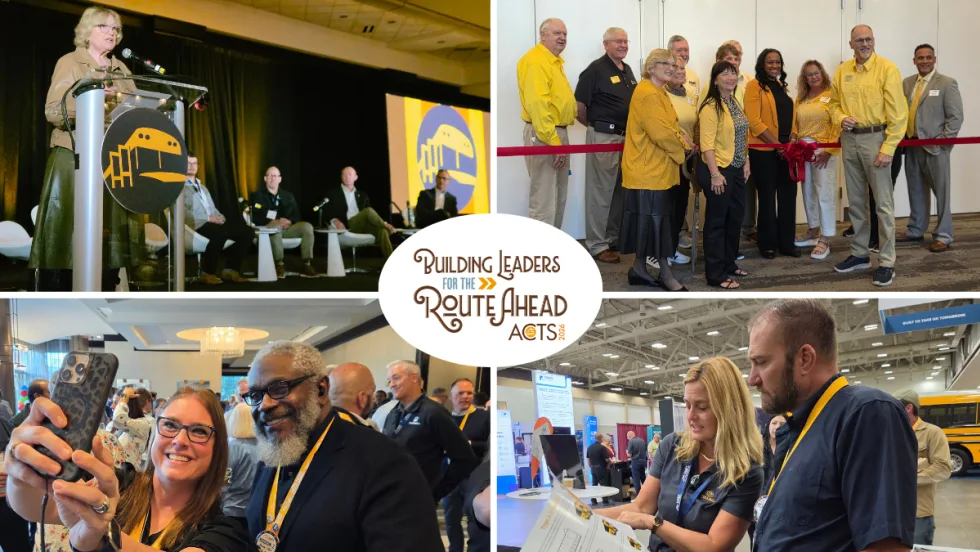
Inside NAPT ACTS 2026: Highlights from Louisville
From federal updates and student behavior strategies to new school bus technology and industry awards, see highlights from NAPT ACTS 2026 in Louisville.
Read More →
Meet the 2026 School Bus Driver Hero Winner: Annette Brown
We caught up with Wa-Nee Community Schools' Annette Brown on site at SBFX, where she was named the 2026 School Bus Driver Hero Award winner. Hear about her reaction, what she loves most about being a school bus driver, and more!
Read More →